Background: Romania’s political turbulence dates back to late 2024, when the Constitutional Court annulled the first round of the presidential election. Centrist Nicușor Dan won the May 2025 rerun, and Ilie Bolojan of the PNL1 (center-right) formed a four-party pro-EU coalition with the PSD2 (center-left), USR3 (center-right), and UDMR4 (center-right). The government raised VAT and other taxes and froze public wages to tackle the EU’s largest deficit, which had hit 9.3% of GDP in 2024 and narrowed to 7.9% in 2025. The PSD quit the coalition in late April 2026, and on May 5 a no-confidence motion filed by the PSD and AUR5 (far-right) toppled Bolojan, leaving an interim cabinet in charge for more than five months.
During our research trip to the region a year ago, the key question was whether Romania could deliver fiscal consolidation. During our recent visit, the question was who would be left in charge of delivering it, and whether markets and rating agencies would wait long enough to find out. Both questions have since been answered, at least for now.
Romania’s domestic political arithmetic is unforgiving. Parliament is split roughly into thirds between the Social Democrats (PSD, center-left), the center-right and the nationalist right (represented by anti-establishment AUR), and the Liberals (PNL, center-right), who refuse to govern alongside the PSD. After three prior unsuccessful attempts over the last six months to form a government, the country was facing the risk of early elections. The stalemate was broken after the president nominated Luca Niculescu, an independent career diplomat who coordinated Romania’s OECD accession. On October 20, parliament approved Niculescu’s minority cabinet by 280 votes to 58, with the PSD and several other parties backing it under a six-month support deal while a longer-term arrangement is negotiated. The outcome avoids the PSD–AUR combination that worried investors most, but the deal is explicitly temporary, and the parties behind it remain far apart on austerity.
The fiscal picture is still in focus. The 6.2% of GDP deficit target for 2026 is described as a firm commitment, and both the EC and the finance ministry see it as achievable, with some upside. The harder task is 2027. With Recovery and Resilience Facility (RRF6) money ending, Romania loses about 1.5% of GDP in externally funded investment, so public investment must be cut just to keep the deficit stable. Brussels expects the deficit at 5.2–5.3% of GDP next year, which requires roughly one percentage point of consolidation and new measures. A full government can now revise the budget, which the interim cabinet could not, but the public wage law did not pass and pension indexation is still an issue. If corrective action stalls, the excessive deficit procedure could escalate, with knock-on effects for EU payments in 2028.
EU flows are a key swing factor. Romania is racing to submit its final RRF7 payment requests, worth around €6 billion, before the year-end deadline. The new SAFE8 defense facility has been a positive surprise, at €2.5 billion this year and an expected €6.5 billion in 2027, broadly offsetting lost RRF loans. On grants, however, the net loss is estimated at 0.7–0.8% of GDP. Growth is weaker than budgeted, foreign direct investment (FDI) is falling, and the external financing need is still large.
On ratings, S&P’s review was days away during our visit. Locals expected the agency to hold off until a government was in place, and one fund manager noted that nearly all of S&P’s questions concerned politics rather than macro. That proved right: S&P affirmed Romania at BBB- with a negative outlook, noting that fiscal consolidation and EU fund absorption had stayed on track in 2026 despite the deadlock. Its baseline assumes a government that adopts a credible 2027–2028 budget framework, with the deficit falling to 6.25% of GDP this year, 5.8% in 2027, and 5.0% in 2028. It named a prolonged government formation, failure to deliver a credible fiscal path, and external pressures such as an energy shock as downgrade triggers and noted that gridlock had already cost €750 million in RRF grants over the stalled wage law.
Hungary
Background: Viktor Orbán’s Fidesz (right) governed Hungary for 16 years, a period that ended with billions of euros in EU funds frozen over rule-of-law concerns, inflation peaking above 25% in early 2023, and two years of near-stagnation. On April 12, 2026, Péter Magyar’s Tisza (center-right) won 53% of the party vote and 141 of 199 seats, a two-thirds constitutional majority, on turnout of nearly 79%. Parliament elected Magyar prime minister on May 9, and his government has since audited the public finances, amended the 2026 budget, and made euro adoption a central policy goal.
Budapest felt transformed. Last year, the conversation centered on whether change was even possible. This time, we met a new Tisza government that is moving quickly on fiscal repair and has set its sights on euro adoption. Among local investors, the mood has swung from habitual pessimism to open optimism. One described Hungary as “the only long end to buy in the whole world.”
Finance ministry officials described the fiscal inheritance in stark terms. The deficit had been running at 8.3% of GDP, driven by spending outside the budget and loosely controlled state-owned enterprises (SOEs). Early cuts, along with the unlocking of about €10 billion in EU funds, brought the starting point down to around 7.5%, roughly where the finance ministry sees this year’s outturn. The budget was amended in August to fund delayed investments and to start removing what officials call “wasteful expenditure,” meaning overpriced procurement contracts, as well as spending on sports, state media, and SOEs. They described savings of 2–3% of GDP as being possible and argued that cutting overpricing should not weigh much on growth.
Since our visit, the 2027 budget was presented by PM Magyar on October 18. It targets a deficit of 4.9% of GDP, and the finance ministry’s medium-term path brings it to 4.0% in 2028, 3.4% in 2029, and 2.8% in 2030, below the 3% required by Maastricht and the exchange rate mechanism (ERM II9) (Figure 1 - below). The budget assumes 2.4% growth and 3% average inflation in 2027, with public debt edging down from 77.5% of GDP this year to 77.2% at end-2027.
Fig. 1
Hungary: General Government Balance
% of GDP
Euro adoption is the defining new theme. The government plans to start ERM II negotiations after the convergence plan is submitted and 2032 is the earliest realistic date for adoption. The NBH10 has lowered its inflation target to 2.5% from January 2028, a move one person we met suspected was partly meant to push the government to deliver on fiscal consolidation.
On monetary policy, the NBH sounded cautious. Core inflation has surprised to the downside, especially in food and durable goods, as the stronger forint fed through to prices faster than expected. Inflation expectations fell sharply after the election. Still, rising fuel and transport costs are a concern, and officials said they were ready to run tighter policy in the short term if needed.
We came away from our meetings with a strong positive view, as the process of Eurozone accession provides a powerful commitment to sound macroeconomic policy. We also appreciate the government’s broad structural agenda, while noting that implementation carries risk. Officials want to shift FDI toward higher value-added sectors such as pharma, medical technology, and defense. They are reviewing the Paks II nuclear project, diversifying uranium supply, and building a multi-year gas price hedging program with the finance ministry. Household energy subsidies cost about 1% of GDP. Potential growth is still below 2%, investment is weak, and labor hoarding is at record highs, so growth is the main risk to the story.
Poland
Background: Prime Minister Donald Tusk’s coalition, led by his Civic Coalition, KO11 (center), has governed since December 2023, but the August 2025 inauguration of President Karol Nawrocki, backed by PiS12 (right), brought a record number of vetoes, including of revenue-raising measures. The deficit reached 7.3% of GDP in 2025 as defense spending climbed, and public debt passed 60% of GDP (EU definition) in early 2026. The Middle East conflict that began early this year triggered an energy price shock across the region, and on September 18, Moody’s cut Poland to A3 from A2, the lowest rating since 2002.
Last year, we described Warsaw’s mood as “comfortable complacency.” This year, the comfort is gone. The energy shock from the Middle East conflict has pushed inflation back above target, the central bank is preparing to reverse course, and a large fiscal deficit now sits alongside a Moody’s downgrade and an election a year away.
Inflation is the immediate problem. September’s flash CPI reading came in at 4%, above the upper end of the National Bank of Poland’s (NBP13) 2.5% ±1 percentage point tolerance band. With the policy rate at 3.75%, the easing cycle never really finished and now the pressure is to hike. Underlying pressures are still contained so far: super-core inflation is 2.7%, wage growth has slowed to below 6%, and inflation expectations show no signs of de-anchoring. Views on hikes ranged widely. One local investor expected up to 100 basis points (bps) over six months, while a local economist doubted the NBP would hike at all unless oil stays high, putting 75 bps as the most hawkish case. Markets were pricing about 125 bps in monetary policy tightening.
Growth is still a bright spot. GDP is running near the NBP‘s 3.9% projection, supported by EU-funded investment and resilient, if slowing, consumption. Credit demand is strong across segments, and large projects are now generating fresh demand for loans.
Fiscal policy offers little relief. The finance ministry projects a general government deficit of 7.1% of GDP for both 2026 and 2027. Defense spending reaches 4.8% of GDP on a cash basis, part of it financed outside the state budget through SAFE14 and U.S. loans. Election pledges are a risk, and several tax measures depend on the president’s signature; without it, revenues would fall. Public debt is likely to breach the 55% of GDP threshold set out in the Public Finance Act. Under that law, the breach triggers mandatory corrective budgeting two years later. Locals expect the deficit to widen in 2028, with major consolidation only around 2030. The Moody’s downgrade barely registered politically, however, and while the deficit is a problem, “but the lack of measures is even more concerning,” per one official.
Politics are increasingly fragmented ahead of the autumn 2027 election. According to a political consultant, Civic Coalition (KO15, center) leads with about 30%, followed by right PiS16 at 20%, followed by two far-right parties; analysts also flagged that polls may understate support for the right wing. PiS has also split, with former PM Morawiecki launching his own party (center-right). While the potential outcomes are varied, a right/far-right win would likely mean renewed tension with Brussels. Meanwhile, a dispute over appointments to the NBP’s management board, which must be resolved by early November, adds to the domestic ‘noise.’
Czechia
Background: Andrej Babiš’s ANO17 (right) won the October 2025 election with 34.5% of the vote and formed a coalition with the SPD18 (far-right) and the Motorists, AUTO19 (right). The cabinet was sworn in on December 15, 2025, and won a confidence vote in January 2026, replacing Petr Fiala’s center-right government, which had prioritized fiscal consolidation after inflation peaked at around 18% in 2022. The CNB20 had halved its policy rate from 7% to 3.5% by mid-2025, but this year’s energy shock has revived inflation risks just as the new government loosens fiscal policy.
Prague is still the region’s low-volatility market, but the ground is shifting. Prime Minister Babiš’s government is loosening fiscal policy at the same time as the energy shock lifts the inflation outlook. As a result, a Czech National Bank (CNB) that recently looked set to ease is now debating whether to hike.
The fiscal turn is clear. The finance ministry expects the deficit to widen from 2.7% of GDP this year to 3.5% in 2027 and says the overshoot above 3% will be temporary. The structural primary balance moves from -1.1% to -2.0% of GDP, which implies a fiscal impulse of about 1% of GDP. Locals see no concrete consolidation measures in the pipeline and find the plan to backload adjustment into an election year hard to believe. The new spending covers green-energy fees, extraordinary pension increases, higher defense spending, infrastructure, and public-sector wages, which will rise 5–9% next year. Public debt is projected to rise from 44.2% of GDP in 2025 to 49.5% in 2029, and interest costs could climb from 1.4% to as much as 2% of GDP. Not everyone was alarmed, however. One official called the fiscal debate a “storm in a glass of water” given low debt and modest deficits, and the finance ministry expects public debt to stay within both EU and national limits.
On monetary policy, the CNB held rates in September but sent a hawkish message, given a tight labor market, wages outpacing productivity, fast credit growth, and fiscal loosening. However, it seems like there is no consensus among board members on whether to hike. CNB forecasts expect inflation to exceed 3% in early 2027, as energy prices pass through over roughly two years and the koruna, long “rock solid,” softens. Markets were pricing about three hikes over 12 months.
The real economy is losing momentum. Revised data show GDP close to stagnation, with near-zero productivity growth, and CNB staff expect quarterly growth of 0.4–0.5%. The auto sector is a bright spot, with record output and Škoda holding its own against Chinese competition, including in EVs (Figure 2 - below). The current account is seen as cyclically pressured by energy rather than structurally impaired. Mortgage rates are heading toward 5.5%, which is cooling housing demand.
Fig. 2
Skoda EV
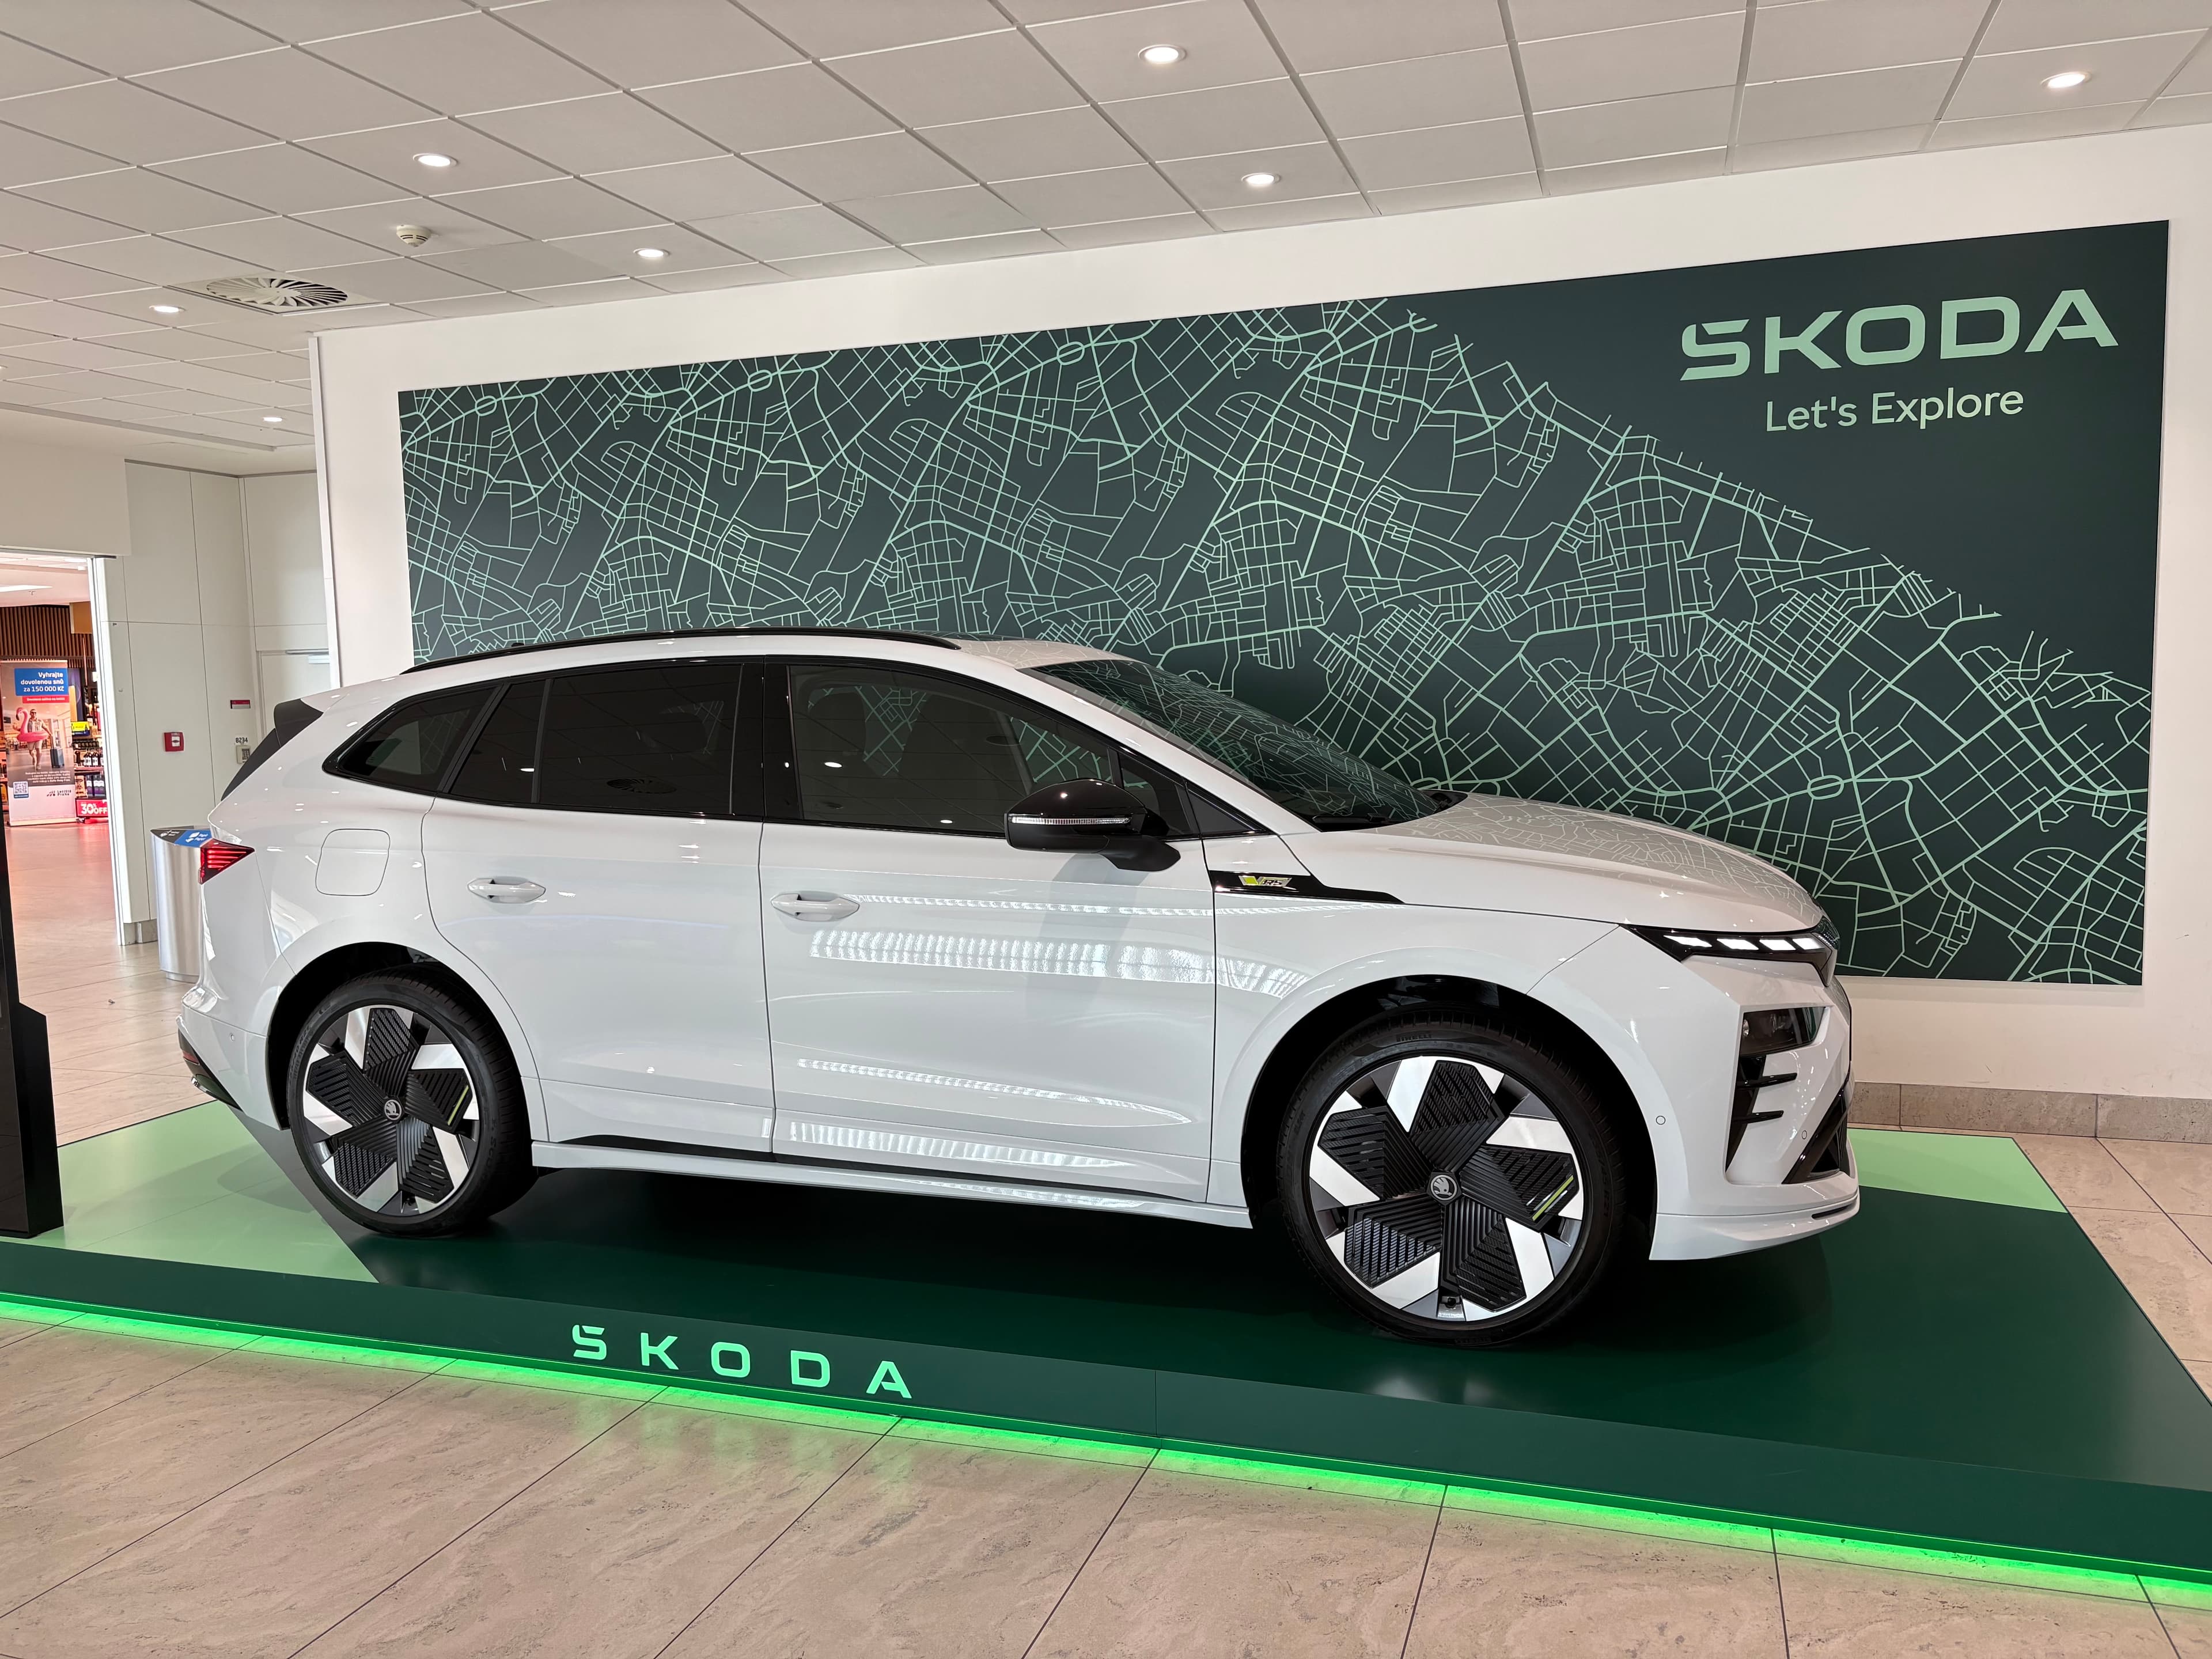
Source: Photograph by author
Portfolio Implications
Romania: The new government and S&P’s affirmation remove the most immediate tail risks, but neither settles the 2027 consolidation question, and a six-month support deal leaves the political runway short. We have reduced exposure to the local markets, while keeping an overweight to hard currency sovereign bonds as we balance fiscal and political risks with still-attractive valuations versus similar-rated emerging markets peers.
Hungary: The story has shifted from political risk to policy credibility, and the 4.9% deficit target for 2027 passes the first test. While hard currency sovereigns seem fully valued, portfolios are still long local government bonds as a medium-term convergence trade towards Eurozone yields.
Poland: Local investors described bonds as “incredibly cheap,” and the local currency has weakened. However, we remain skeptical given the near-term volatility of oil and direction of both monetary and fiscal policy. We are also concerned with the lack of visibility ahead of next year’s election. Given that view, portfolios are still underweight both hard currency sovereigns and local government bonds, with the latter also serving as a hedge against Eurozone volatility.
Czechia: Deep domestic savings still anchor CZGBs21, but fiscal loosening, a hawkish-leaning CNB, a softer koruna, a possible major index exit next year, make us cautious. We close our short EURCZK as monetary policy risks disappointing market expectations and Eurozone volatility is elevated, and remain marketweight local duration.
Footnotes:
PNL: National Liberal Party (Partidul Național Liberal), Romania; center-right.
PSD: Social Democratic Party (Partidul Social Democrat), Romania; center-left.
USR: Save Romania Union (Uniunea Salvați România); center-right.
UDMR: Democratic Alliance of Hungarians in Romania (Romániai Magyar Demokrata Szövetség); center-right.
AUR: Alliance for the Union of Romanians (Alianța Pentru Unirea Românilor); far-right.
RRF: Recovery and Resilience Facility, the EU’s post-pandemic grant and loan program (NextGenerationEU).
RRF: Recovery and Resilience Facility, the EU’s post-pandemic grant and loan program (NextGenerationEU).
SAFE: Security Action for Europe, the EU’s defense loan instrument.
ERM II: Exchange Rate Mechanism II, under which a currency is held within a band against the euro for at least two years before euro adoption.
NBH: National Bank of Hungary (Magyar Nemzeti Bank).
KO: Civic Coalition (Koalicja Obywatelska), Poland; center.
PiS: Law and Justice (Prawo i Sprawiedliwość), Poland; right.
NBP: National Bank of Poland (Narodowy Bank Polski).
SAFE: Security Action for Europe, the EU’s defense loan instrument.
KO: Civic Coalition (Koalicja Obywatelska), Poland; center.
PiS: Law and Justice (Prawo i Sprawiedliwość), Poland; right.
ANO: ANO 2011(Czech for “yes”), the party of Andrej Babiš; right-wing populist.
SPD: Freedom and Direct Democracy (Svoboda a přímá demokracie), Czechia; far-right.
AUTO: Motorists for Themselves (Motoristé sobě), Czechia; right.
CNB: Czech National Bank.
This material is intended solely for institutional investors and is not intended for retail investors or general distribution. This material may not be reproduced or distributed without Payden & Rygel’s written permission. This presentation is for illustrative purposes only and does not constitute investment advice or an offer to sell or buy any security. The statements and opinions herein are current as of the date of this document and are subject to change without notice.
This material has been approved by Payden & Rygel Global Limited, a company authorised and regulated by the Financial Conduct Authority of the United Kingdom, and by Payden Global SIM S.p.A., an investment firm authorised and regulated by Italy’s CONSOB. It is directed exclusively at professional investors or eligible parties and counterparties as defined by the rules of the Financial Conduct Authority or, for EU jurisdictions, by the rules of the Markets in Financial Instruments Directive (“MiFID”), as transposed in the relevant EU jurisdictions, and is not intended for use by retail investors. Suitability/appropriateness of the investment is the responsibility of the investor, no assurance can be given that any stated investment objectives will be achieved, and the value of investments may fall as well as rise. This information does not constitute an invitation or offer to subscribe for or purchase any products mentioned which will only be accepted on the basis of the relevant prospectus. The law may restrict distribution of this information in certain jurisdictions, therefore, persons into whose possession this message comes should inform themselves about and observe any such restrictions.
Past performance is no indication of current or future performance, and that it does not take account of the commissions and costs incurred on the issue and redemption of shares.
For institutional use only—not for public distribution.